

Esaurito ma molto ricercato!
Maggiori informazioni sul libro
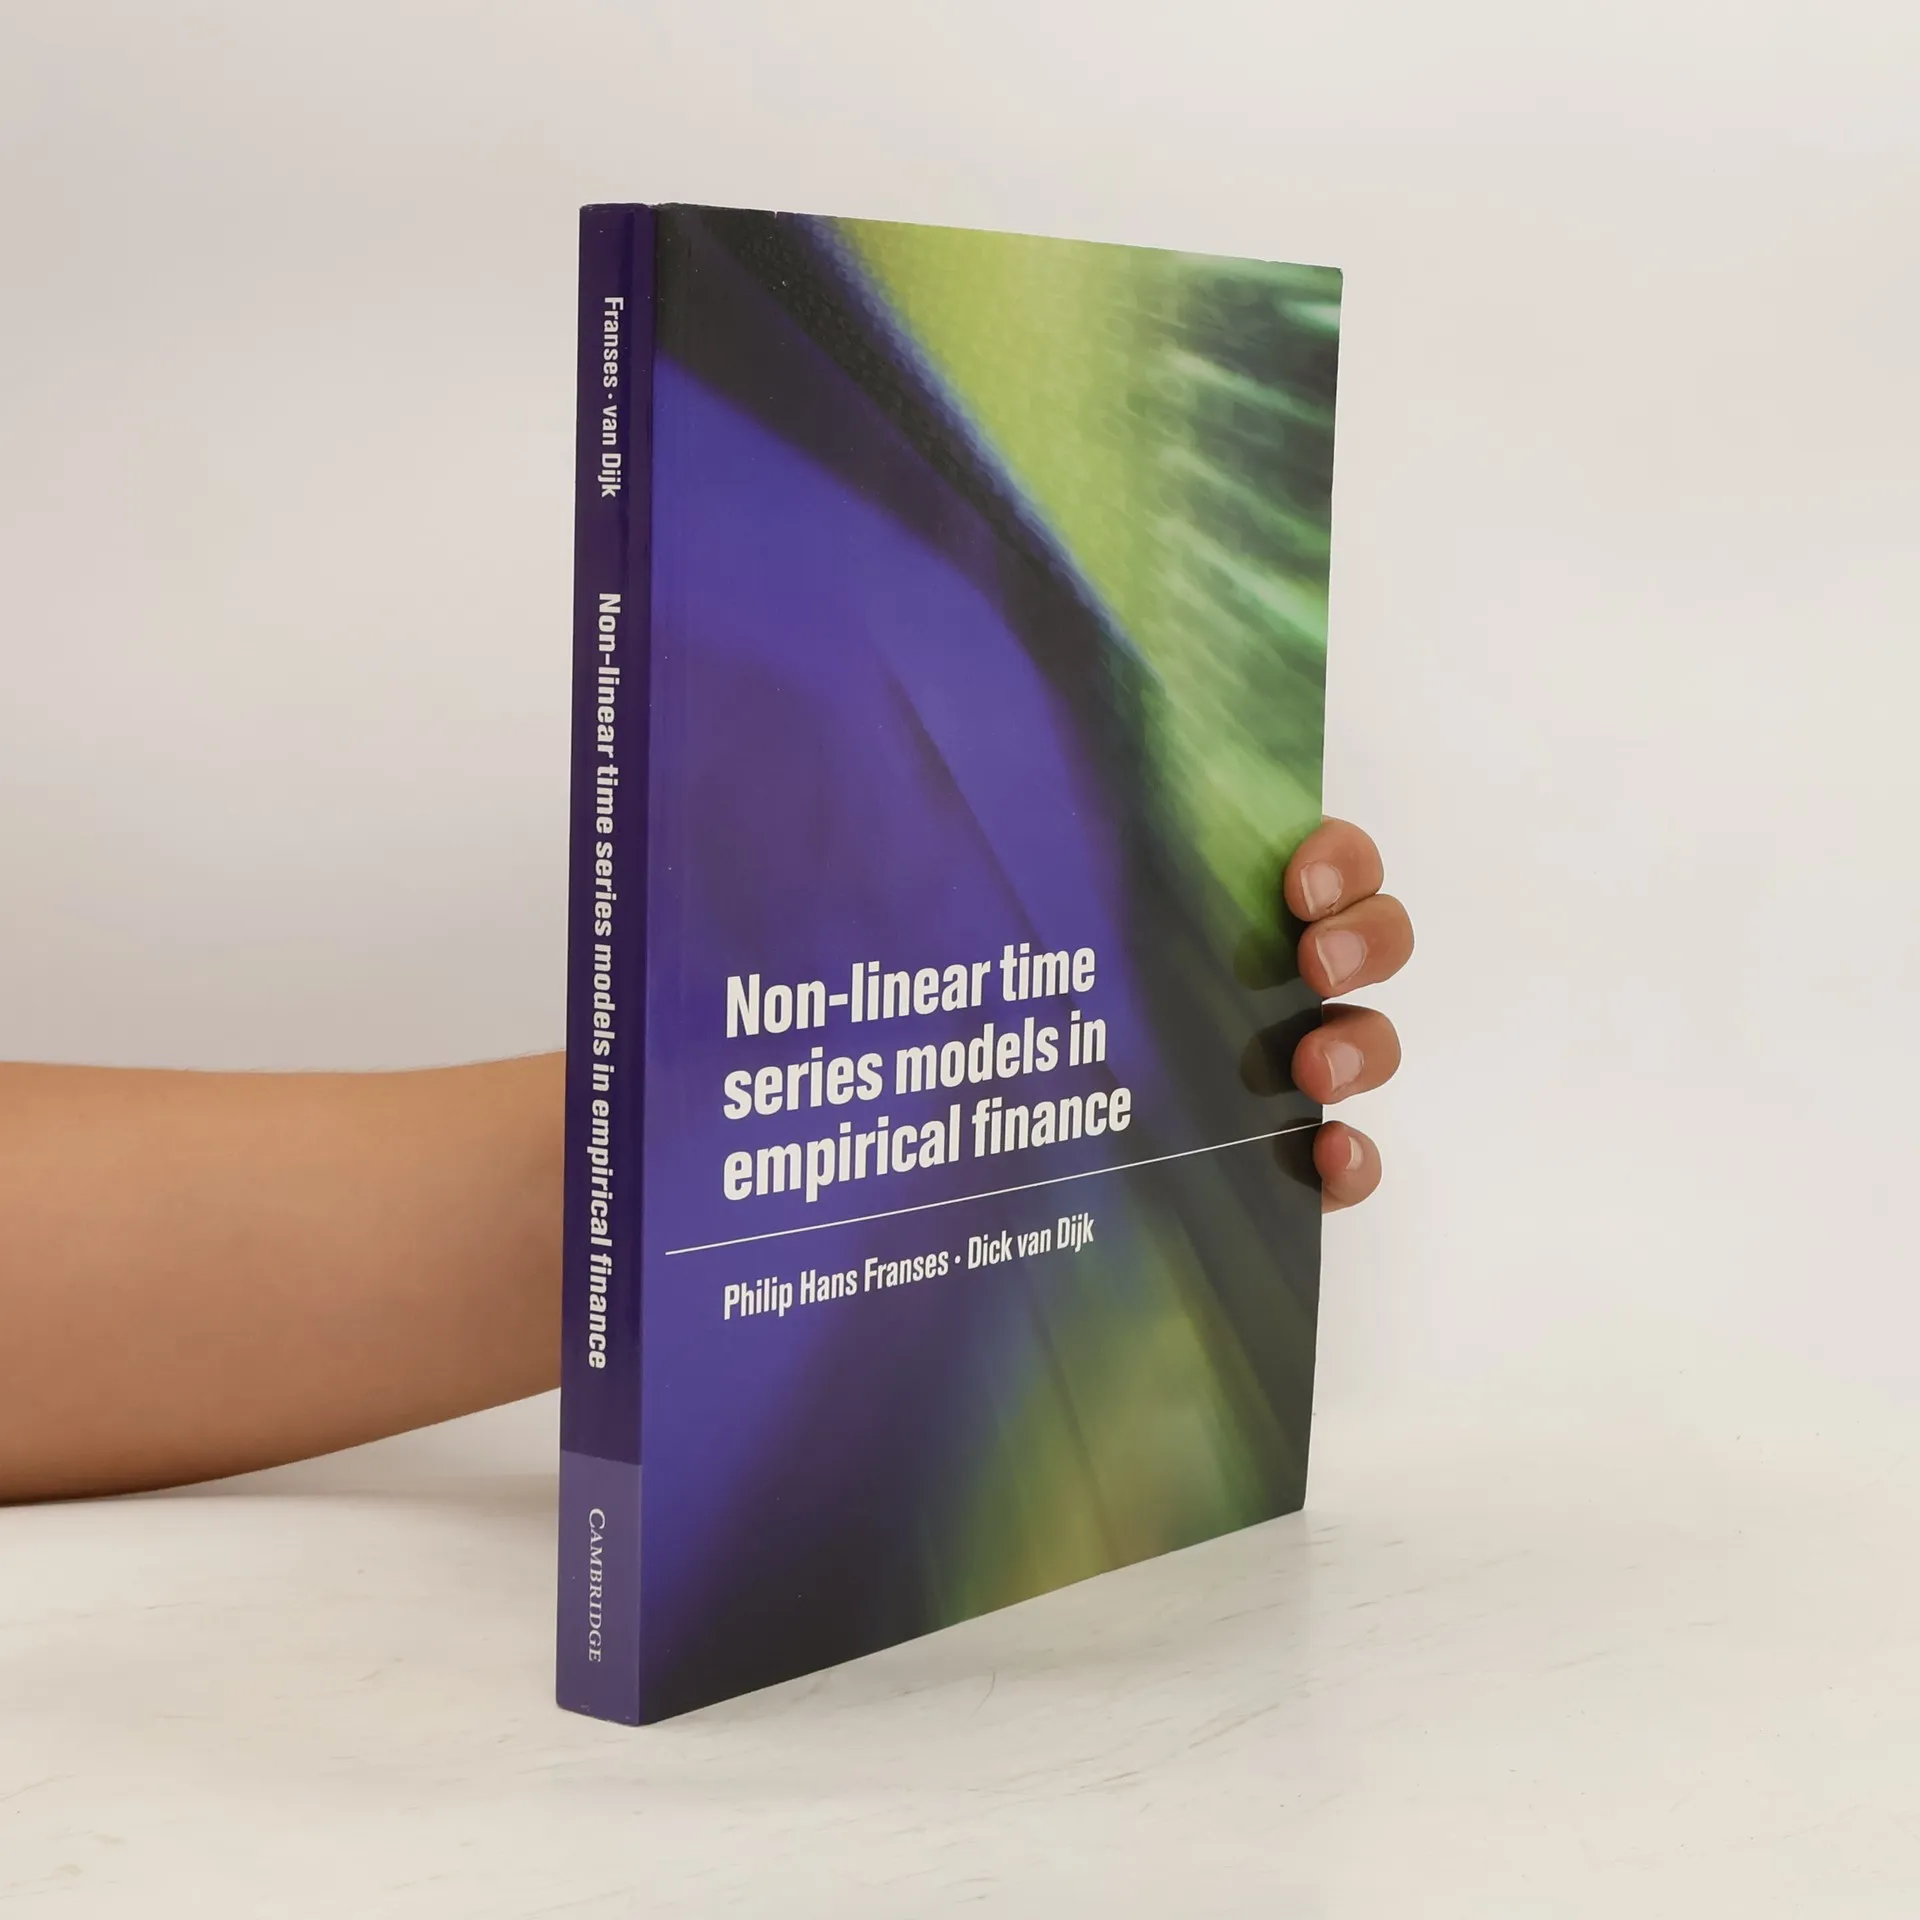
This is the most up-to-date and accessible guide to one of the fastest growing areas in financial analysis by two of the most accomplished young econometricians in Europe. This classroom-tested advanced undergraduate and graduate textbook provides an in-depth treatment of recently developed nonlinear models, including regime-switching and artificial neural networks, and applies them to describing and forecasting financial asset returns and volatility. It uses a wide range of financial data, drawn from sources including the markets of Tokyo, London and Frankfurt.
Acquisto del libro
Non-Linear Time Series Models in Empirical Finance, Philip Hans Franses, Dick van Dijk
- Lingua

- Pubblicato
- 2000
- Rilegatura
- (Rilegatura flessibile)
Ti avviseremo via email non appena lo rintracceremo.
Metodi di pagamento
Qui potrebbe esserci la tua recensione.
- Titolo
- Non-Linear Time Series Models in Empirical Finance
- Lingua
- Inglese
- Autori
- Philip Hans Franses, Dick van Dijk
- Editore
- Cambridge University Press
- Pubblicato
- 2000
- Formato
- Rilegatura flessibile
- Pagine
- 296
- ISBN10
- 0521779650
- ISBN13
- 9780521779654
- Serie
- Categoria
- Tag
- Commercio
- Valutazione
- 3,65 su 5
- Descrizione
- This is the most up-to-date and accessible guide to one of the fastest growing areas in financial analysis by two of the most accomplished young econometricians in Europe. This classroom-tested advanced undergraduate and graduate textbook provides an in-depth treatment of recently developed nonlinear models, including regime-switching and artificial neural networks, and applies them to describing and forecasting financial asset returns and volatility. It uses a wide range of financial data, drawn from sources including the markets of Tokyo, London and Frankfurt.